
Anthropic’s Series H in May 2026 set its post-money valuation at about $965 billion, and in June it confidentially submitted a draft S-1 to the SEC. This article breaks down the funding ladder, revenue metrics, and listing progress. It is a summary of public information, not investment advice. For background, start with What kind of company is Anthropic.
Remember one thing first: “private valuation,” “annualized revenue,” and “full-year actual revenue / public share price” are three different things.
A Three-Step Jump in Eight Months: The Funding and Valuation Ladder
| Round | Date | Amount Raised | Post-Money Valuation |
|---|---|---|---|
| Series A | 2021 | ~$124 million | Not disclosed |
| Series F | September 2025 | ~$13 billion | ~$183 billion |
| Series G | February 2026 | ~$30 billion | ~$380 billion |
| Series H | May 2026 | ~$65 billion | ~$965 billion |
(Rounds B through E are left out; only the largest recent milestones are listed.)
In about eight months, the post-money valuation jumped from $183 billion to $380 billion and then to $965 billion. Series H was led by Altimeter, Dragoneer, Greenoaks, and Sequoia, and valued Anthropic above OpenAI’s March 2026 round at about $852 billion. As of October 2026, it is still Anthropic’s latest private valuation.
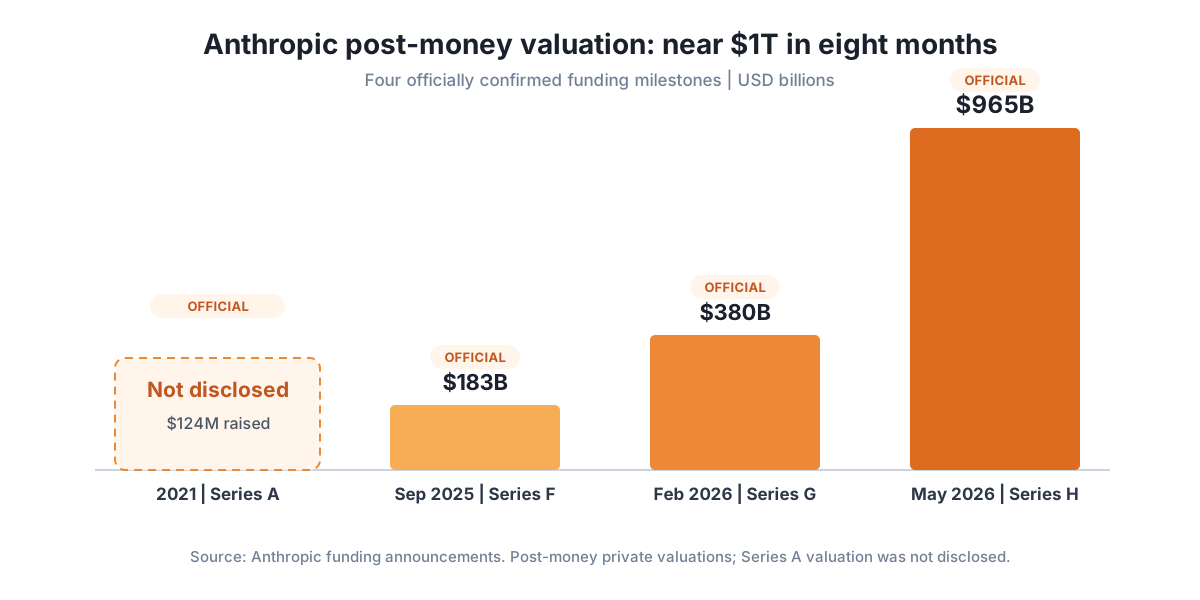
This is a private-market valuation: a price a few investors agreed on in one round, not a share price traded every day on a public market.
ARR Is Not the Same as Actual Revenue
Officially announced ARR (annualized revenue): over $5 billion in August 2025, $14 billion in February 2026, and over $47 billion in May. According to Bloomberg, it passed $65 billion by the end of July 2026.
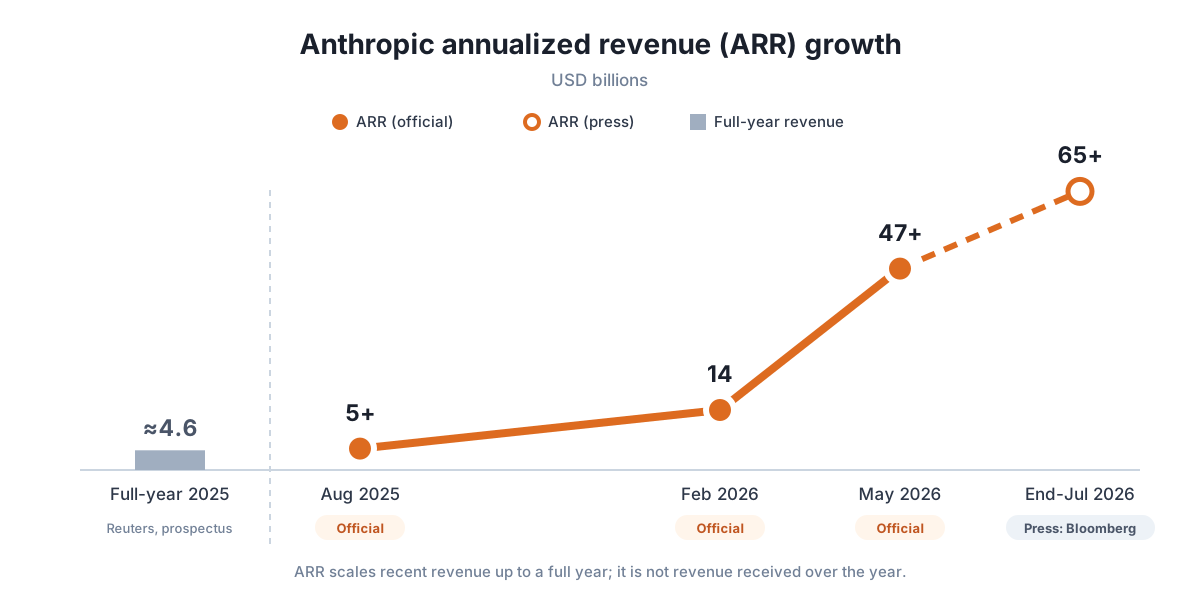
ARR takes recent revenue and multiplies it out to a full year. It shows speed, not the full-year result. Example: ARR was already above $5 billion in August 2025, but according to the prospectus seen by Reuters, 2025 full-year revenue was nearly $4.6 billion.
Other financial figures reported by the media:
- 2025 losses (Reuters, prospectus): an operating loss of more than $8 billion; a net loss of about $42 billion, of which about $34 billion was non-cash accounting charges.
- Q2 2026 (Bloomberg, preliminary figures): revenue above $11.5 billion, with adjusted operating profit turning positive (excluding stock-based compensation).
These are all media reports. Anthropic has not confirmed them, and the public S-1 is not out yet.
In one sentence: ARR is the speedometer for “how fast it’s going,” not the odometer for “how far it went over the full year.”
How the Valuation Is Calculated: Three Views in the Market
The market reads the same $965 billion in three ways. They are listed here to show where the debate is, not to ask you to pick a side.
- The optimists: enterprise AI spending will keep growing and Claude’s enterprise customers are sticky, so a very high revenue multiple is justified.
- The neutrals: the growth is real, but the price already reflects a lot of good news. What matters next is whether revenue and profit deliver.
- The conservatives: ARR may overstate real revenue, and losses and compute costs are large. This price treats optimistic expectations as fact.
The three views differ in their assumptions: ARR or full-year revenue, what multiple to use, and whether profit can improve. Change the assumptions and the “fair valuation” changes a lot.
Behind the Valuation: The Compute Commitments on Its Shoulders
Anthropic does not make its own chips. Its compute comes through long-term contracts with partners such as AWS, Google, and Microsoft Azure. According to the prospectus seen by Reuters, its cloud, compute, and infrastructure commitments total about $518 billion.
The flip side of a high valuation is high commitment: if growth goes well, these contracts are fuel; if growth slows, they become a heavy bill. For how the compute side works, see Anthropic’s compute gamble.
S-1 and IPO Progress
Anthropic confidentially submitted a draft S-1 to the SEC on June 1, 2026. As of October 2026, the public S-1, ticker symbol, and listing date have not been announced.
Plans reported by the media:
- Timing: according to Bloomberg in early October, the formal roadshow could start as soon as the week of November 9, with a target of listing before Thanksgiving (November 26) and no later than year-end.
- Exchange: reportedly Nasdaq.
- Valuation: Bloomberg reported that potential investors are looking at $1.8 trillion to $2 trillion; Reuters reported it could exceed $2 trillion.
- Underwriting banks: reportedly Morgan Stanley, Goldman Sachs, JPMorgan, and Citi.
The schedule has already slipped once and may change again before final pricing. For what a confidential submission is and which numbers to watch once the S-1 is public, see Anthropic IPO explained.
Shares cannot be bought on an exchange before the listing. After it lists, readers outside the US usually buy US stocks through an international broker. For brokers that may offer the shares later, see the IBKR account opening guide and the Firstrade guide; to choose between them, see IBKR vs. Firstrade. These explain the channels and are not recommendations.
Penchan’s summary
Anthropic’s valuation is a snapshot of the AI investment boom: the growth is real, the price the market is willing to pay is real, and a layer of assumptions sits between them.
Public information only, not investment advice. Fuller history: Pre-IPO deep-dive report. Further reading: What kind of company is Anthropic, Anthropic vs OpenAI, Why a public benefit corporation.
Understanding how a number is measured matters more than memorizing the number itself.